

This page explains the basic ideas of accounting with the example of a new business.
An Example Business
You start a home interior business. These are the first four events of the business:
- Owner investment: You put ₹5,00,000 of your money in the bank account of the business.
- Rent: You rent a co-working space for ₹40,000 a month. This is the first expense. The bank balance is now ₹4,60,000.
- First sale: A customer pays ₹30,000 at once. This is the first income. The bank balance is now ₹4,90,000.
- Web agency: You hire a web agency to make a website for ₹50,000. You pay the agency after two months. No money leaves the bank account now, but the business must pay in the future. This amount is a liability. You record it in Accounts Payable.
The Five Types of Accounts
Each account has one of five types. This table puts the four events into the types and shows the balances.
| Type | Contains | Accounts in the Example | Balance |
|---|---|---|---|
| Asset | What the business owns | Bank | ₹4,90,000 |
| Liability | What the business owes to others | Accounts Payable | ₹50,000 |
| Equity | What the owners put in the business, and the profits that it keeps | Capital | ₹5,00,000 |
| Income | What the business earns | Sales | ₹30,000 |
| Expense | What the business spends to do its work | Rent, Website | ₹90,000 |
The balances agree with this rule:
Assets = Liabilities + Equity + Income - Expenses
In the example: ₹4,90,000 = ₹50,000 + ₹5,00,000 + ₹30,000 - ₹90,000.
Account Types in Frappe Books
In Frappe Books, the type of an account is its Root Type. The Standard Chart of Accounts has one root account for each root type:
| Root Type | Root Account | Example Accounts |
|---|---|---|
| Asset | Application of Funds (Assets) | Cash, Debtors, your bank accounts |
| Liability | Source of Funds (Liabilities) | Creditors, Secured Loans |
| Equity | Equity | Capital Stock, Retained Earnings |
| Income | Income | Sales, Service |
| Expense | Expenses | Office Rent, Travel Expenses |
All the accounts below a root account have the root type of that account. For more information, see Chart of Accounts.
Credit and Debit
A debit increases some accounts and decreases other accounts. A credit does the opposite.
| Root Type | A Debit | A Credit |
|---|---|---|
| Asset | Increases the balance | Decreases the balance |
| Expense | Increases the balance | Decreases the balance |
| Liability | Decreases the balance | Increases the balance |
| Equity | Decreases the balance | Increases the balance |
| Income | Decreases the balance | Increases the balance |
Frappe Books shows each balance on the side that increases it. In the Chart of Accounts, the balance of an Asset or an Expense account ends with Dr.. The balance of a Liability, an Equity, or an Income account ends with Cr..
Double-Entry Bookkeeping
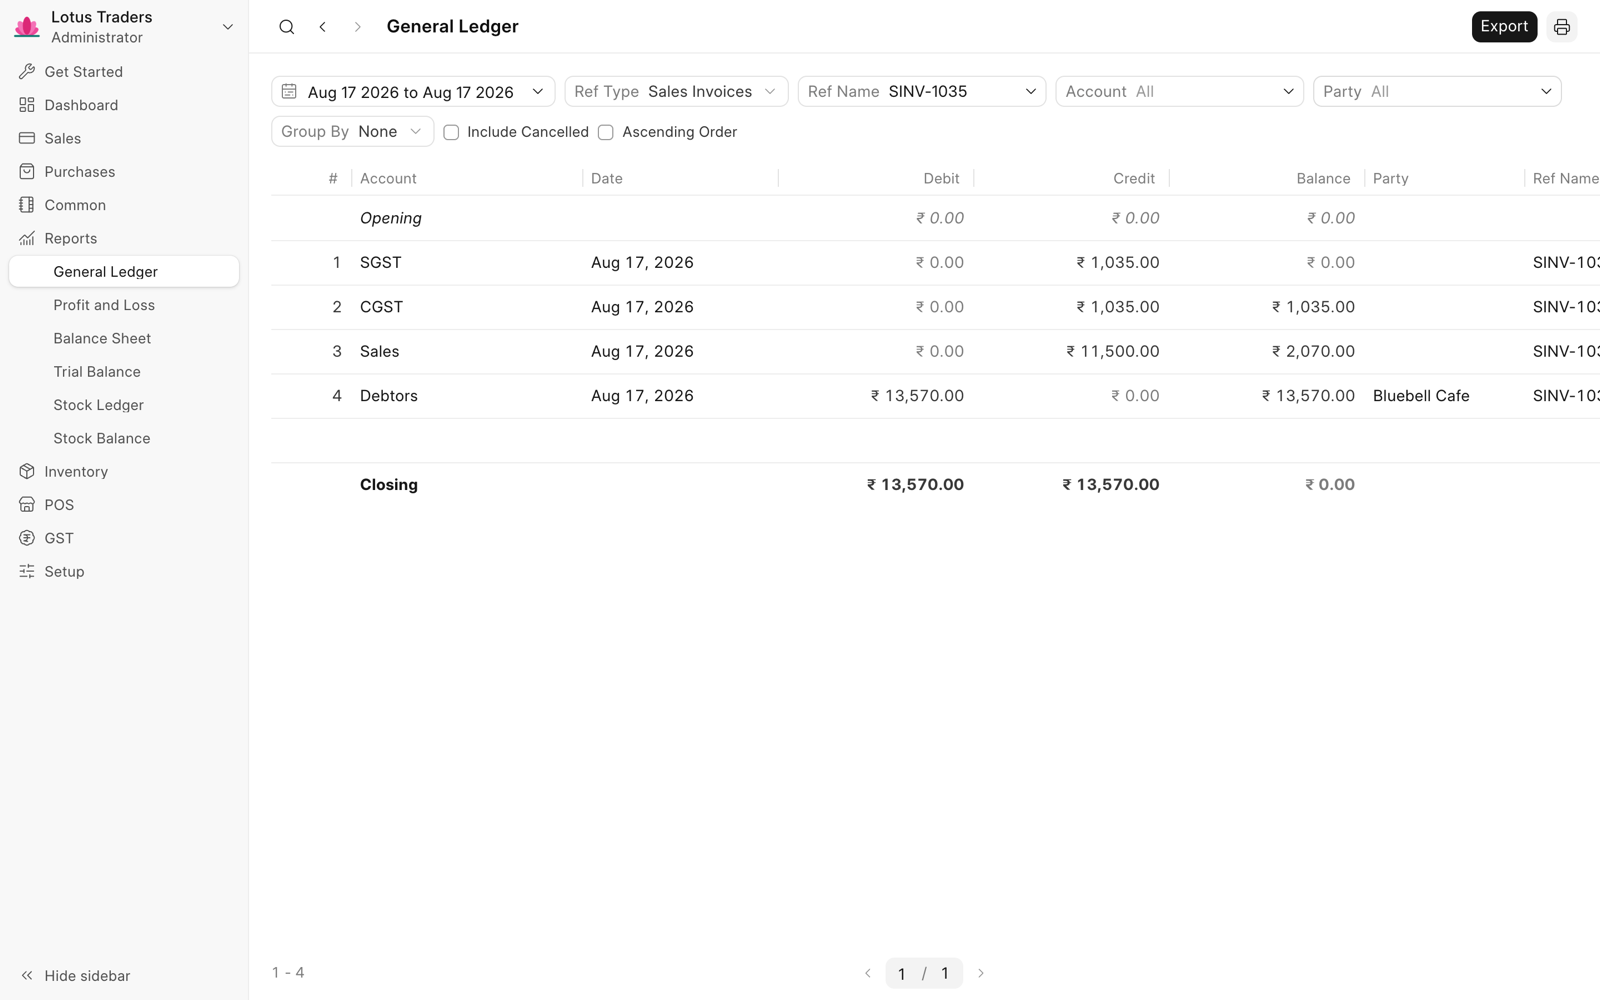
Each event changes at least two accounts. In each event, the total of the debits is equal to the total of the credits. This is the basis of double-entry bookkeeping. The four events of the example make these entries:
| Event | Account | Debit | Credit |
|---|---|---|---|
| 1. Owner investment | Bank (Asset increases) | ₹5,00,000 | |
| Capital (Equity increases) | ₹5,00,000 | ||
| 2. Rent | Rent (Expense increases) | ₹40,000 | |
| Bank (Asset decreases) | ₹40,000 | ||
| 3. First sale | Bank (Asset increases) | ₹30,000 | |
| Sales (Income increases) | ₹30,000 | ||
| 4. Web agency | Website (Expense increases) | ₹50,000 | |
| Accounts Payable (Liability increases) | ₹50,000 |
To see the entries of a document in Frappe Books, submit a sales invoice. Then click View > Accounting entries in the page header. The General Ledger opens with the debit or the credit of each account.